
Commercial Auto Insurance in Austin, TX
Protect business vehicles, drivers, and operations with commercial auto coverage structured around how your company actually uses the road.
// AUSTIN BUSINESS VEHICLE PROTECTION
WHAT IS COMMERCIAL AUTO INSURANCE?
Commercial auto insurance is designed for vehicles used in business operations. It may cover eligible company cars, pickups, vans, service vehicles, and other vehicles used for work.
A policy may combine auto liability with physical-damage and other optional protections. What applies depends on vehicle ownership, drivers, business use, limits, deductibles, exclusions, and insurer requirements.
Risk Coverage Insurance helps Austin and Central Texas businesses compare available commercial auto options based on how their vehicles are actually used.

WHAT MAY COMMERCIAL AUTO INSURANCE COVER?
Commercial auto insurance may combine liability protection for injuries or property damage you cause with coverage for eligible insured vehicles. Actual protection depends on the policy terms, selected options, drivers, vehicles, and business use.
Bodily Injury Liability
May help pay eligible injury-related damages when a covered driver causes an accident that injures another person.
Property Damage Liability
May help pay for eligible damage a covered driver causes to another person’s vehicle, building, fence, sign, or other property.
Collision Coverage
May help repair or replace an insured business vehicle after an eligible collision with another vehicle or object.
Comprehensive Coverage
May help with eligible non-collision losses such as theft, hail, fire, vandalism, falling objects, or similar covered events.
Uninsured/Underinsured Motorist Coverage
May help with eligible losses when an insured vehicle or occupant is involved in an accident caused by a driver with no insurance or insufficient liability limits.

Hired and Non-Owned Auto
May address certain business-liability exposures involving rented, leased, borrowed, or employee-owned vehicles used for covered business purposes.
WHO SHOULD CONSIDER COMMERCIAL AUTO INSURANCE?
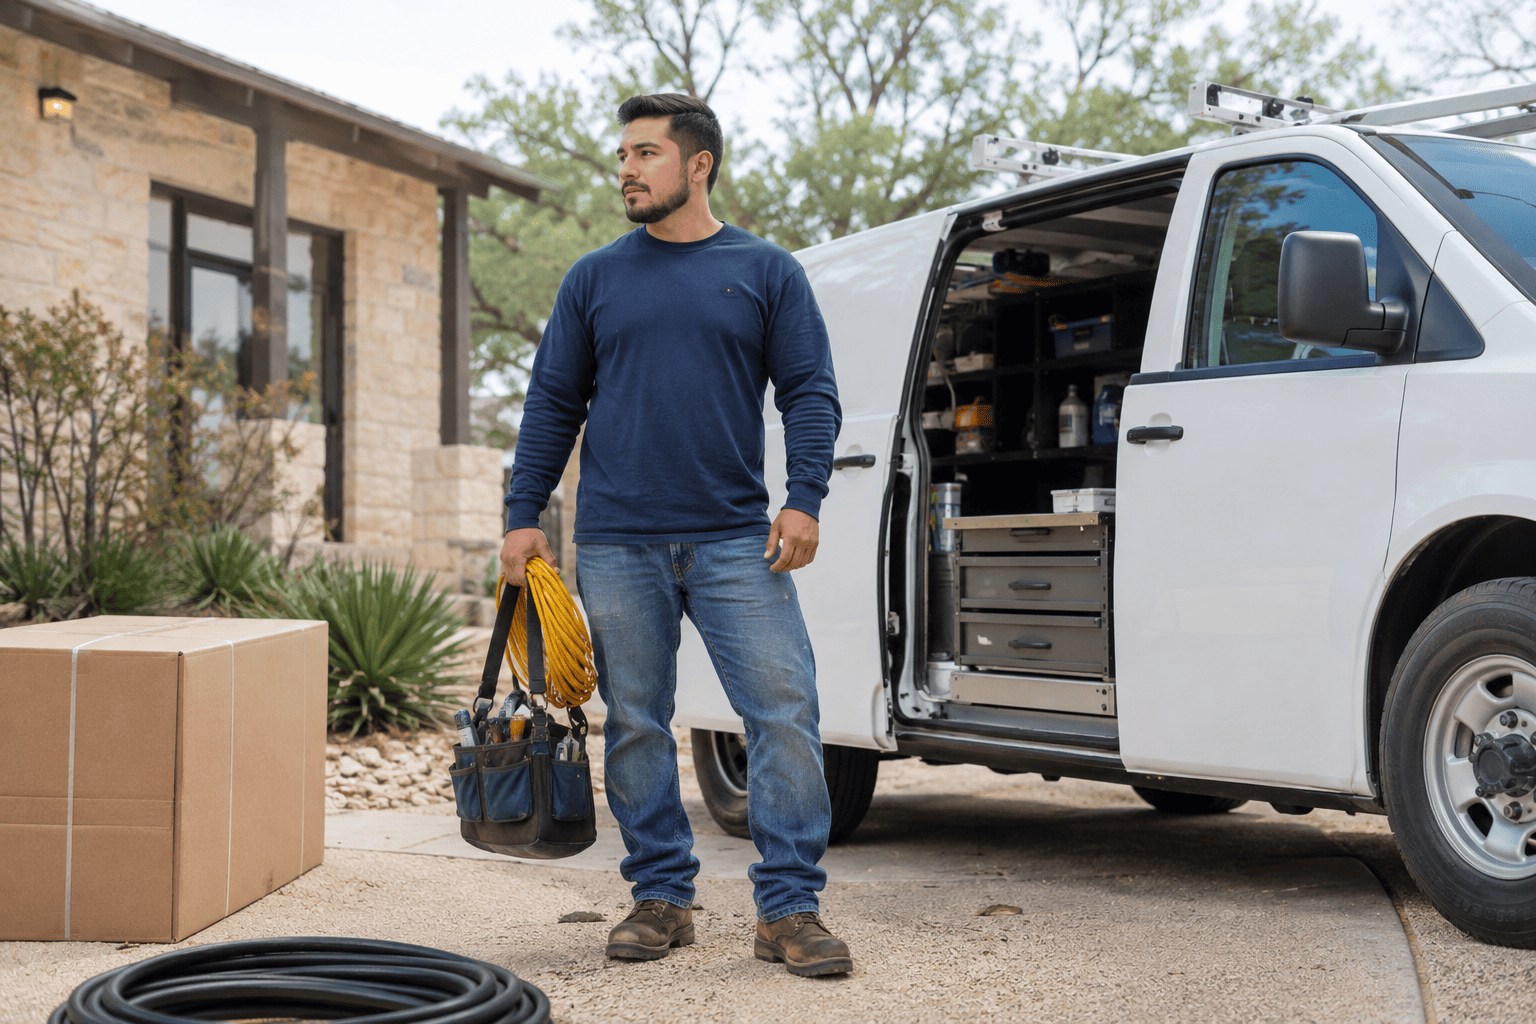
Businesses should review commercial auto insurance when vehicles are company-owned, regularly used for work, driven by employees, or used to visit customers, job sites, or other business locations.
This can include contractors, delivery businesses, service companies, sales teams, property-service companies, restaurants with delivery operations, and businesses using pickups, vans, or other work vehicles.
The key question is not simply who owns the vehicle. How it is used, who drives it, where it travels, and what business activity it supports all matter.
WHAT AFFECTS COMMERCIAL AUTO INSURANCE COST?
Insurers evaluate the vehicles, drivers, and business activity behind them rather than pricing every company the same way.
Vehicle type, age, value, and weight
Driver history and motor-vehicle records
Annual mileage and operating territory
Prior accidents and claims
Number of insured vehicles
How each vehicle is used
Customer, delivery, or job-site driving
Coverage limits, deductibles, and selected options
A local service vehicle making short Austin trips presents a different exposure than a vehicle traveling long distances, making frequent deliveries, or carrying specialized equipment.
COMMERCIAL AUTO VS. PERSONAL AUTO INSURANCE
Both insure vehicles, but they are designed around different ownership and use patterns. Regular business use can create exposures that a personal auto policy was not structured to address.
Commercial Auto Insurance
Designed around eligible vehicles and driving exposures connected to business operations.
Common situations may include:
- Business-owned vehicles
- Employee drivers
- Customer or job-site travel
- Delivery or service routes
- Tools or equipment transported for work
- Multiple business vehicles
Personal Auto Insurance
Designed primarily around personal and household vehicle use.
Common situations may include:
- Personal commuting
- Household errands
- Family drivers
- Recreation
- Ordinary personal travel
Do not assume a personal auto policy automatically covers regular business driving. Ownership, frequency of use, driver activity, and business purpose should be reviewed before selecting the policy type.
WHAT COMMERCIAL AUTO INSURANCE USUALLY DOES NOT COVER
What Happens When a Claim Exceeds Your Limit?
A commercial auto liability policy generally pays no more than the applicable liability limit for a covered claim.
A serious accident involving multiple injuries or substantial property damage can exceed the available limit. Amounts above the policy limit may create financial exposure for the business or another legally responsible party.
Compare limits against vehicle use, contracts, business assets, driving frequency, and potential claim severity rather than choosing limits based only on premium.
What Commercial Auto Usually Does Not Cover
Commercial auto insurance does not cover every driver, vehicle, activity, or property exposure. Common exclusions or gaps may include:
- Undisclosed or ineligible drivers
- Vehicles not covered by the policy
- Unapproved vehicle uses
- Intentional or criminal acts
- Mechanical breakdown
- Normal wear and tear
- Business-owned tools or equipment
- Cargo or customer property
- Employee workplace injuries
- Losses above applicable limits
Separate policies or endorsements may be needed for property, employee, cargo, equipment, or other exposures outside commercial auto coverage.
IMPORTANT COMMERCIAL AUTO INSURANCE DECISIONS
Confirm Every Driver and Use
Review who drives each vehicle, where it travels, how frequently it is used, and whether employees use rented, borrowed, or personal vehicles for business.
Match Coverage to Vehicle Value
Consider vehicle value, repair cost, financing requirements, deductibles, and whether collision and comprehensive coverage fit the financial exposure.
Review Coverage
Review the policy after adding drivers or vehicles, expanding territory, changing business use, increasing deliveries, or taking contracts that create different transportation exposures.
Related Coverage Options
Commercial auto addresses business-driving exposure. These related coverages may address risks that arise outside the vehicle itself.
General Liability Insurance
May address eligible third-party bodily injury, property damage, and other liability claims arising from business operations.
Collision Coverage
May help with eligible physical damage when an insured vehicle collides with another vehicle or object.
Uninsured/Underinsured Motorist Coverage
May help with eligible losses when an at-fault driver has no liability insurance or insufficient limits.
// faq
COMMERCIAL AUTO INSURANCE FAQS
WHAT DOES COMMERCIAL AUTO INSURANCE COVER?
Commercial auto insurance may include liability, collision, comprehensive, uninsured or underinsured motorist coverage, and other options depending on the vehicles, drivers, business use, selected protections, and policy terms.
DOES MY BUSINESS NEED COMMERCIAL AUTO INSURANCE?
A business should review commercial auto coverage when it owns vehicles, employees regularly drive for work, or vehicles are used for deliveries, customer visits, job sites, or other commercial activities.
CAN A PERSONAL VEHICLE USED FOR BUSINESS BE COVERED?
Possibly. The appropriate coverage depends on vehicle ownership, frequency and type of business use, who drives it, and insurer eligibility requirements.
WHO CAN DRIVE MY BUSINESS VEHICLES?
Coverage depends on the policy’s driver requirements, listed or eligible drivers, exclusions, covered vehicles, and circumstances of the trip.
WHAT IS HIRED AND NON-OWNED AUTO COVERAGE?
Hired auto generally refers to certain rented, leased, or borrowed vehicles used for business. Non-owned auto may address certain liability exposures when employees use vehicles the business does not own for covered business activities.
DOES COMMERCIAL AUTO COVER TOOLS OR EQUIPMENT IN THE VEHICLE?
Commercial auto primarily addresses vehicle and auto-liability exposures. Business tools, equipment, cargo, or customer property may require separate insurance depending on the policy and property involved.
WHAT IS THE DIFFERENCE BETWEEN COLLISION AND COMPREHENSIVE?
Collision generally addresses eligible damage caused by impact with another vehicle or object. Comprehensive generally addresses eligible non-collision losses such as theft, hail, fire, vandalism, or falling objects.
HOW MUCH COMMERCIAL AUTO LIABILITY COVERAGE SHOULD MY BUSINESS CARRY?
There is no single limit appropriate for every business. Consider vehicle type, driving frequency, operating territory, contracts, business assets, and potential accident severity when comparing limits.
//Talk to an Insurance Expert
COMPARE COMMERCIAL AUTO INSURANCE OPTIONS
Tell us about your business, vehicles, drivers, and current coverage needs. A licensed insurance agent can review your request and discuss available commercial auto options for your Austin or Central Texas business